
Metaplanet sold 10,000 BTC and bought back 11,000 at a higher average price to show it was willing to sell its Bitcoin.
The Japanese treasury company was pursuing a credit rating and better access to financing, and its Oct. 5 disclosure explained why turning coins into cash was part of that effort. Prospective creditors needed confidence that management could use its holdings to meet obligations, even if shareholders bought into the company because of those holdings.
Proving the point was expensive, with Metaplanet receiving ¥124.7 billion from the sale and spending ¥149.9 billion on the subsequent purchase, paying roughly 9.3% more per coin.
Applying that average purchase price to the 10,000 coins replaced produces a price difference of about ¥11.57 billion, before transaction costs and potential tax effects. That gives shareholders an expensive receipt for the demonstration.
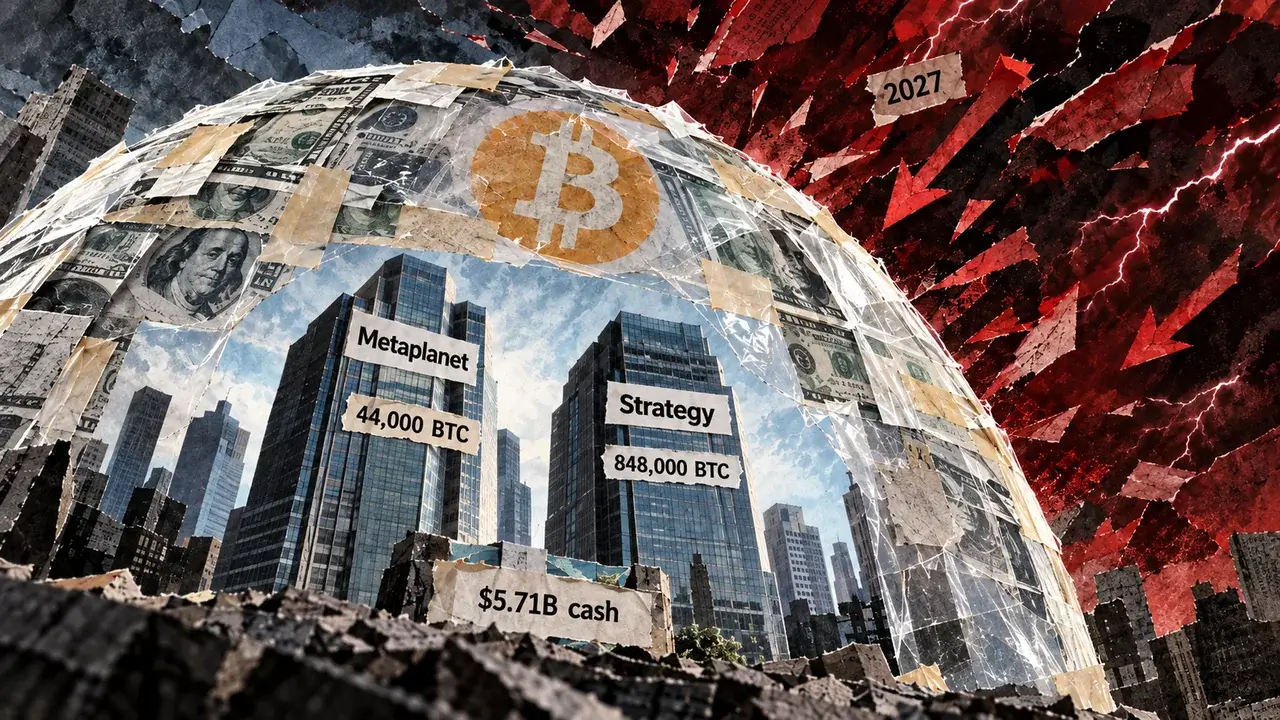
The company didn’t use the proceeds to repay borrowings or bonds, and it ended September with 44,000 BTC. Selling was part of an effort to improve the financing behind continued accumulation.

That brings us to the strange relationship underlying the corporate Bitcoin trade. Shareholders are usually happy to wait years for a higher price, but lenders have contracts that specify when they want their money back. The same reserve has to satisfy both groups.
Lenders would like their money back in dollars
A company that owns an asset as liquid as Bitcoin isn’t quite the same as a company having cash available to pay a bill. Coins may be pledged against borrowing, or management may be unwilling to sell at the available price.
Either way, creditors need to know what happens when the payment date and the preferred selling price don’t cooperate.
Metaplanet’s June financial statement reported ¥67.49 billion in short-term borrowings and ¥8 billion in bonds payable within a year, against ¥1.09 billion in cash and deposits and ¥250 million in USDC.
The numbers exclude the company’s much larger Bitcoin reserve and the financing it could access, so the gap explains why lenders want more than a coin count when assessing repayment.
The contracts give dates to that discussion, although the numbers below come from different reporting periods and shouldn’t be read as a like-for-like comparison of current liquidity.
Sources: Metaplanet’s bond terms, June accounts, and October disclosure; Strategy’s June filing and October update.
Strategy’s notes technically mature in September 2028, but the holder’s right to demand repayment brings a potential cash obligation forward by a year.
Its June filing also lists roughly $4.9 billion of notes with similar holder repurchase rights during 2028, taking the principal associated with those 2027 and 2028 dates to about $5.91 billion.
Holders must exercise their rights, and conversions or repurchases could reduce those amounts before then, meaning the company has clear points when access to cash is more important than confidence in Bitcoin’s eventual price.
This is why corporate Bitcoin has financing deadlines even though Bitcoin itself doesn’t expire. Management can borrow again, issue securities, or use cash to meet obligations, but those options have their own costs, and they aren’t equally attractive in every market.
Keeping Bitcoin takes money that isn’t Bitcoin
Strategy has built a sizable dollar cushion, giving it more room. Its Oct. 5 filing reported a $4.88 billion dedicated reserve and another $833.4 million in separate dollar-denominated cash, totaling approximately $5.71 billion as of Oct. 4.
The dedicated reserve supports preferred-stock dividends and debt interest, and its policy requires board authorization for other uses. The separate cash balance provides a lot of flexibility, so adding the two together doesn’t make the entire sum an unrestricted pot for future debt repayments.
The same filing shows how much work now goes into managing the coins’ financing. Between Sept. 28 and Oct. 4, Strategy used $142.5 million from its reserve for dividends and interest, spent $154.1 million on repurchasing preferred shares, and bought $13 million of Bitcoin.
Strategy still held 848,000 BTC, bought for about $63.97 billion, so Bitcoin dominates the balance sheet. But the cash gives management breathing room when payments come due, helping it avoid selling coins simply because the market has chosen an inconvenient week to fall.
Its earlier Bitcoin sales and reserve-building already showed that supporting the securities financing the reserve could take precedence over buying more coins. Keeping some money in dollars can help the company retain Bitcoin through a downturn.
There’s also a shareholder version of the same problem. When a treasury company’s shares trade above the value of the assets behind them, issuing shares can bring in enough money to increase Bitcoin exposure per existing share.
When that premium disappears, the company must give away more ownership to raise the same amount, making the deal less attractive to existing investors.
Metaplanet’s June results said its market-value-to-net-asset-value measure (mNAV) was below 1.0 for much of the period. Its policy generally avoids discretionary common-share issuance below that threshold, so the restriction prevented some fundraising, leaving financing below earlier expectations.
The company continued buying through other funding sources, but the experience demonstrates how dilution can complicate accumulation well before anyone faces a forced sale. The reserve can get bigger while an existing shareholder’s economic interest becomes less attractive.
Selling some Bitcoin can be the better option when the alternative is issuing shares cheaply. Preferred shares are one way to do that, but they give investors claims ahead of common shareholders, with the exact payment rights depending on the terms.
Missing a preferred dividend isn’t automatically a bond default, although disappointing those investors can make the next fundraising harder.
The decision is about how much Bitcoin shareholders can afford to keep exposed once everyone financing the company has been accounted for, a less photogenic number than total BTC holdings.
One Bitcoin company starts financing another
Metaplanet is also trying to generate income beyond holding coins, because Bitcoin by itself doesn’t produce the dollars or yen needed to service financing. Its revised allocation policy targets roughly 85% to 90% of assets in Bitcoin and 10% to 15% in strategic investments, including income-producing securities.
Its Net Interest Income Strategy seeks to earn more from those investments than it pays to finance them. Possible investments include preferred securities issued by other Bitcoin treasury companies, meaning one company’s plan to support its Bitcoin reserve could include collecting payments from another company facing a similar challenge.
That could provide recurring cash for financing costs or further purchases, but it also creates the possibility of exposure to the same weakness twice. Falling Bitcoin prices could reduce Metaplanet’s core asset value, while securities issued by other treasury companies could lose value or become less dependable income sources.
The policy acknowledges potential correlation, and the actual risk depends on what the company buys and how it finances those investments. It shows how far the business can travel from the simple proposition of buying shares in a company that owns Bitcoin.
Across the rest of the market, these financing arrangements make corporate purchases less permanent than the accumulation announcements can make them feel. Companies can keep believing in Bitcoin while slowing purchases, building cash, or selling coins because the terms available to their shareholders have deteriorated.
Voluntary sales and forced liquidations are different events, and neither company’s disclosures establish an imminent liquidation. The more immediate consequence can be a buyer spending its next dollar on financing obligations.
Metaplanet’s round trip still has to earn its keep through better credit access or borrowing terms, since the disclosure doesn’t prove a rating agency ordered the sale or that cheaper financing has been secured.
Strategy’s cash cushion buys flexibility, but how much depends on the obligations it needs to cover and the capital it can raise later.
Both cases make the same point about holding Bitcoin through a corporate balance sheet: keeping the coins requires decisions about the money around them.
Management willing to sell some Bitcoin on sensible terms may do more for shareholders than management defending a never-sell promise by borrowing expensively or handing away too much ownership to keep it.